Choosing to pursue higher education or professional development is a significant investment, both in time and money. When you start exploring your options, one of the first figures you'll encounter is tuition, often seen as the primary cost. However, tuition is just one piece of a much larger financial puzzle. To truly understand the full financial commitment involved, you need to look beyond the sticker price.
This is where the "Cost of Attendance" (COA) comes in. Often overlooked or misunderstood, COA is a comprehensive estimate of all educational expenses for a student during a given academic year. It's the total sum that colleges and universities calculate to represent the maximum amount of financial aid you can receive, encompassing far more than just what you pay directly to the school. Understanding your COA is fundamental to smart planning, borrowing wisely, and moving forward with confidence.
Beyond Tuition: What Exactly is COA?
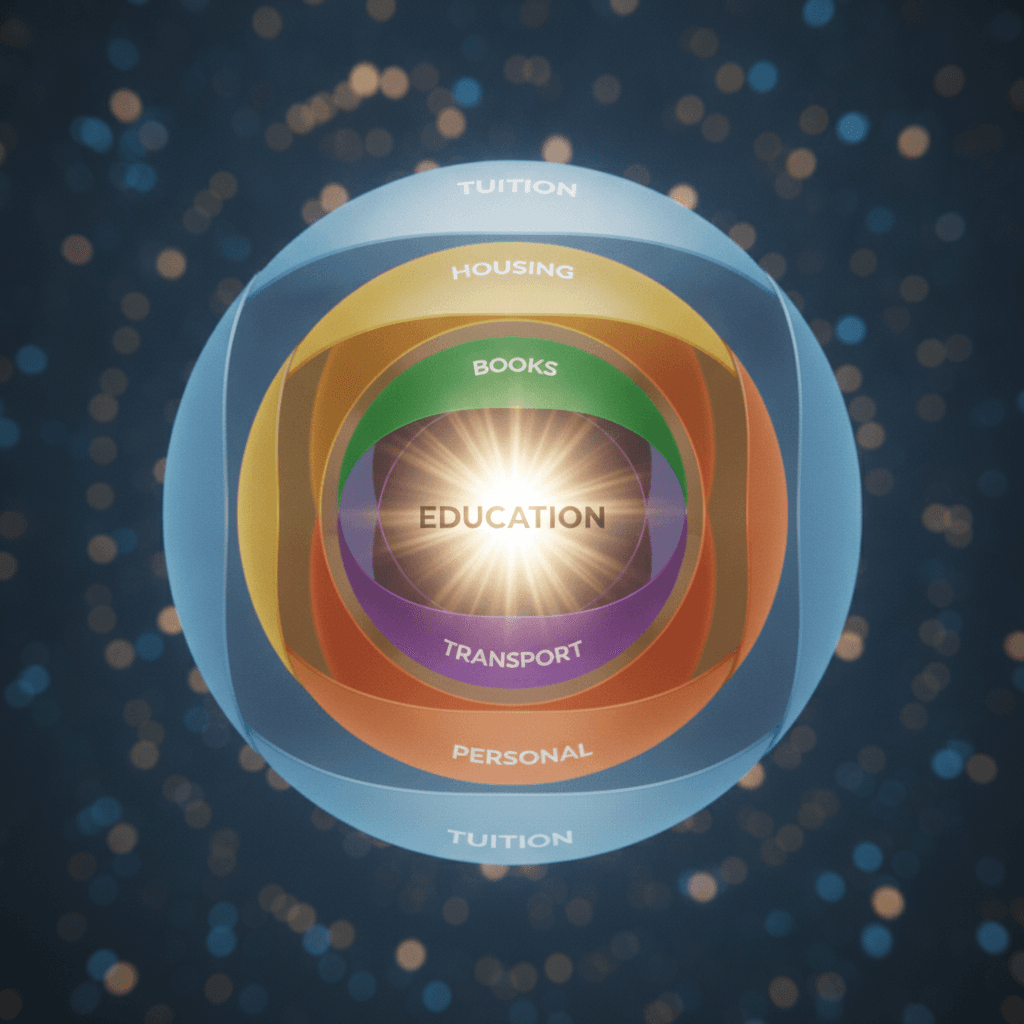
The Cost of Attendance (COA) is a key figure determined by each educational institution. It represents the total estimated cost to attend that school for a specific period, usually an academic year. Think of COA as a complete budget rather than just a bill. It's designed to give you a realistic picture of the financial resources you'll need, accounting for both direct charges from the school and other necessary expenses you'll incur.
Crucially, the COA is not the amount you will necessarily pay out of pocket. Instead, it serves as a ceiling for the total amount of financial aid – including grants, scholarships, and loans – that a student can receive. Institutions are required to publish their COA, and it often varies significantly between schools and even between different programs or student living arrangements at the same school.
Key Components of Cost of Attendance
The components of COA are generally categorized into two main types: direct costs and indirect costs. Direct costs are those expenses billed directly by the institution, while indirect costs are estimated expenses that you will pay to other vendors or service providers. Together, these paint the full financial picture.
- Tuition and Fees: The charges for instruction and enrollment in courses, plus any mandatory fees for campus services, technology, or activities.
- Room and Board: The cost of housing (on-campus dorms or an allowance for off-campus rent) and a meal plan or an allowance for food.
- Books and Supplies: An estimate for textbooks, course materials, software, and other academic necessities.
- Transportation: An allowance for travel expenses, whether commuting daily or traveling to and from home during breaks.
- Personal Expenses: A budget for miscellaneous costs such as toiletries, laundry, entertainment, and other day-to-day living expenses.
- Loan Fees: If you take out federal student loans, the origination fees associated with those loans are also factored into the COA.
Direct vs. Indirect Costs: A Closer Look
Let's clarify the distinction between direct and indirect costs, as this is a common point of confusion. Direct costs are the expenses you'll typically see itemized on your bill from the college or university. These are the charges the school expects you to pay directly to them. Tuition, mandatory fees, and on-campus room and board are prime examples of direct costs. These are usually fixed amounts set by the institution.
Indirect costs, on the other hand, are estimated expenses that are not billed by the school but are still essential for your attendance. These include the allowances for books and supplies, transportation, and personal expenses. While these figures are estimates, they represent very real out-of-pocket spending that you will incur. For example, if you live off-campus, your rent and groceries are indirect costs. The school includes these estimates in the COA to ensure that the total financial aid package can cover all reasonable expenses associated with your education, not just the ones they charge you for.
Why COA Matters for Your Financial Aid
Understanding your COA is crucial because it directly impacts the amount of financial aid you can receive. For federal student aid programs, your financial need is calculated by subtracting your Expected Family Contribution (EFC) – a number derived from your FAFSA application – from the COA. The resulting figure is your financial need, and it determines the maximum amount of need-based aid you are eligible for.
Even for non-need-based aid, such as unsubsidized federal student loans or private loans, the COA acts as a cap. You generally cannot receive financial aid that exceeds your institution's calculated Cost of Attendance. This means that if your COA is lower at one school than another, your potential aid package, particularly loan amounts, might also be lower, even if the tuition is similar. Schools use the COA to package grants, scholarships, work-study, and loans, ensuring that the total aid does not surpass the estimated comprehensive cost of attending.
Understanding Your COA: Practical Steps
To effectively utilize the COA in your educational planning, start by locating the specific COA for each institution you are considering. Most schools publish this information clearly on their financial aid websites. Pay close attention to how the COA is broken down, noting the differences between direct and indirect costs, and how various living situations (on-campus vs. off-campus, living with parents) might alter the total.
Remember that while the COA provides a comprehensive estimate, your actual expenses might differ. You have some control over indirect costs. For instance, choosing more affordable housing, carefully budgeting for groceries, or opting for used textbooks can help you keep your personal spending below the estimated allowances. By understanding all the components of the COA, you can make informed decisions about where to apply, how much aid you might need, and how to manage your expenses responsibly throughout your academic journey.
In conclusion, the Cost of Attendance is far more than just a number; it's a powerful tool for financial planning in education. By looking beyond tuition and embracing the full scope of direct and indirect expenses, you gain a clearer picture of the total investment required. This comprehensive understanding empowers you to make smarter choices about financing your education, effectively navigate the financial aid process, and ultimately, move forward confidently towards your academic and career goals.
Sources & Further Reading
- Cost of attendance — Wikipedia
- Student financial aid — Wikipedia
- What is Information Architecture? — Interaction Design Foundation
- How Users Read on the Web — Nielsen Norman Group
- Memory and Learning — Interaction Design Foundation