Navigating the world of college funding can feel like deciphering a complex code, with terms like FAFSA, COA, and EFC often swirling around. Among these, the Expected Family Contribution, or EFC, stands out as a foundational concept. It’s a number that plays a critical role in determining how much financial aid you might qualify for, acting as a gatekeeper to grants, scholarships, and federal loans.
Understanding your EFC isn't just about knowing a figure; it's about grasping the mechanism behind financial aid decisions. For learners and self-improvers making real money-and-education decisions, a clear picture of EFC can help you study smarter, borrow wiser, and move forward with confidence in your educational journey. Let's break down what EFC is, how it's calculated, and what it means for your financial aid prospects.
What Exactly Is Expected Family Contribution (EFC)?
At its core, the Expected Family Contribution (EFC) is an index number that colleges use to determine how much financial aid you are eligible to receive. It's not the amount of money your family will actually have to pay for college, nor is it a bill from a specific institution. Instead, the EFC is an assessment of your family's financial strength and its ability to contribute to your educational expenses for a given academic year.
This number is calculated using a standardized formula established by Congress. Every student who applies for federal student aid through the Free Application for Federal Student Aid (FAFSA) receives an EFC. Colleges then subtract your EFC from their Cost of Attendance (COA) to determine your financial need, which dictates the amount of need-based aid you can receive.
How EFC Is Calculated: The FAFSA Connection
The primary source of information for calculating your EFC is the data you provide on the FAFSA. This application collects detailed financial and demographic information about you and your family. The EFC formula takes into account various factors, weighing them to arrive at a fair, consistent assessment of what your family could reasonably contribute.
It’s important to remember that the formula is designed to be equitable across all applicants. While complex, it generally considers a snapshot of your family's finances from a specific period, known as the 'base year,' which is typically two years prior to the academic year for which you're applying for aid.
- Parent and student income: This includes both taxed and untaxed income from wages, investments, and other sources.
- Parent and student assets: Liquid assets such as savings accounts, checking accounts, certain investments (stocks, bonds, mutual funds), and real estate equity (excluding the primary home) are assessed.
- Family size: The number of dependents in the household.
- Number of family members attending college: Having multiple family members enrolled in college can significantly lower the EFC per student.
- Age of the older parent: This factor is used to calculate an asset protection allowance, which shelters a portion of parent assets from the EFC calculation.
Understanding "Need" and Financial Aid Eligibility
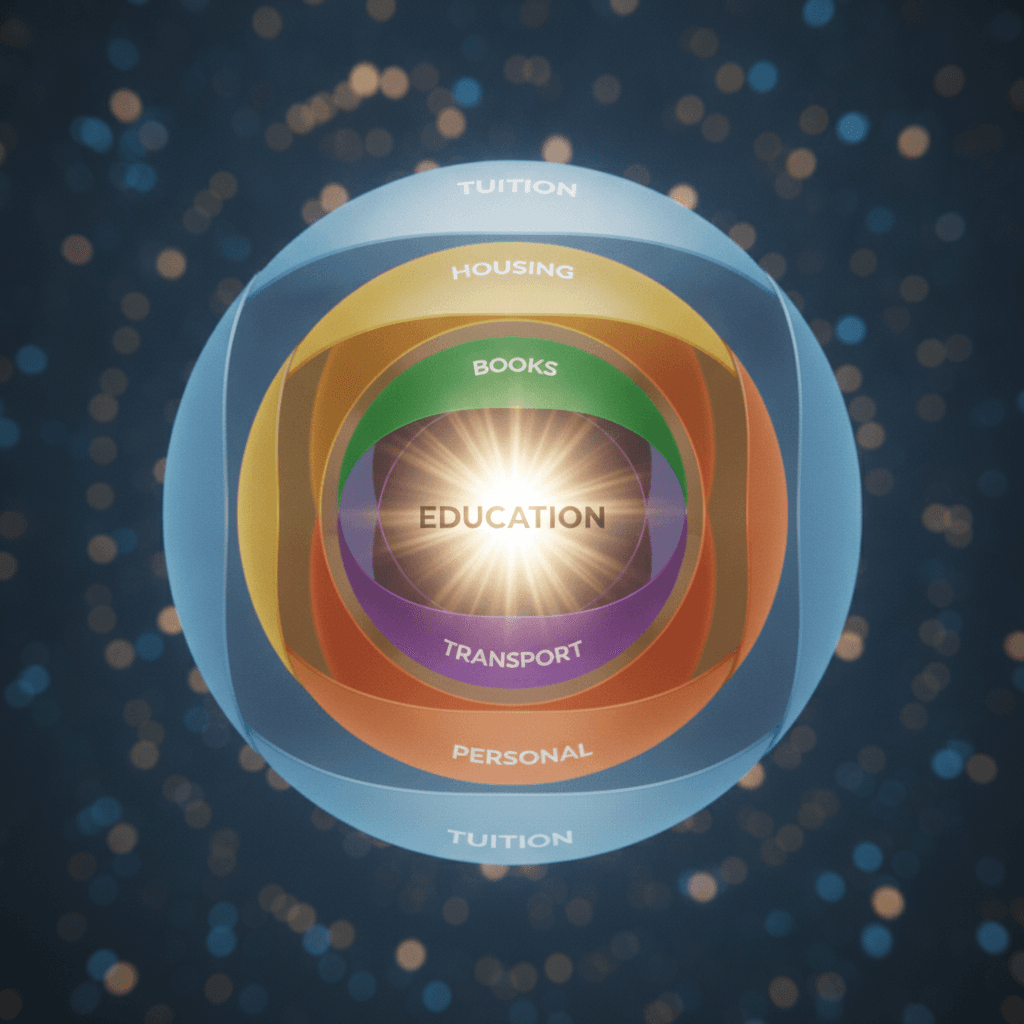
The EFC's most crucial function is to determine your financial 'need.' This is not an arbitrary term; it's a specific calculation that colleges use to award aid. Every college has a Cost of Attendance (COA), which is an estimate of what it will cost to attend that institution for an academic year. The COA includes tuition and fees, room and board, books and supplies, transportation, and personal expenses.
The formula for financial need is straightforward: Cost of Attendance (COA) - Expected Family Contribution (EFC) = Financial Need. For instance, if a college's COA is $30,000 and your EFC is $10,000, your calculated financial need would be $20,000. The college will then try to meet this need through a combination of grants, scholarships, work-study programs, and loans.
EFC vs. What You Actually Pay
One of the most common misconceptions about EFC is that it represents the actual amount a family will pay out of pocket. This is rarely the case. While your EFC indicates your family's calculated ability to contribute, colleges may not always be able to meet 100% of your demonstrated financial need. This can result in a 'gap' between your need and the aid you receive.
The aid package you receive will consist of various types of financial assistance. Grants and scholarships are considered 'gift aid' because they don't need to be repaid. Work-study programs allow students to earn money through part-time jobs. Federal student loans, while needing to be repaid, often come with more favorable terms than private loans. The EFC helps determine your eligibility for these different forms of aid, especially those that are need-based.
General Considerations to Potentially Lower Your EFC
While you cannot directly manipulate the EFC formula, understanding how it works can inform general financial planning. Please remember that these are general educational points and not personalized financial advice; individual situations can vary greatly, and professional guidance is always recommended.
Some common strategies that families consider include: focusing on saving in parent-owned assets rather than student-owned assets, as student assets are assessed at a higher rate; strategically timing income if possible (though this is often difficult); and maximizing contributions to retirement accounts, which are generally not counted in the EFC calculation. Additionally, having more than one child enrolled in college simultaneously can significantly divide the EFC among those students, potentially increasing each student's eligibility for need-based aid.
EFC Moving Forward: The Shift to Student Aid Index (SAI)
It's important to note a significant upcoming change: the FAFSA Simplification Act will replace the term 'Expected Family Contribution' (EFC) with 'Student Aid Index' (SAI) starting with the 2024-2025 award year. While the name changes, the core purpose remains the same: to provide an index number used to determine eligibility for federal student aid.
The new SAI calculation will introduce some changes to the formula, aiming to simplify the application process and potentially expand Pell Grant eligibility for more students. Understanding the principles behind EFC (and soon, SAI) will continue to be vital for anyone planning to pursue higher education and seeking financial assistance. By grasping these concepts, you empower yourself to make informed decisions and better navigate the path to financing your education.
Sources & Further Reading
- What is the Expected Family Contribution (EFC)? — Federal Student Aid
- How Your Expected Family Contribution (EFC) Is Calculated — Federal Student Aid
- Expected Family Contribution — Wikipedia
- Free Application for Federal Student Aid — Wikipedia