Starting higher education involves navigating financial aid. The Free Application for Federal Student Aid (FAFSA) is your gateway, and understanding the new Student Aid Index (SAI) is key to unlocking necessary support. SAI, which replaced the Expected Family Contribution (EFC), is the primary metric colleges use to determine your eligibility for various financial assistance. It’s not a bill, but an index schools use to calculate your financial need. Understanding what the SAI is, how it’s determined, and its implications for education financing is essential for informed decisions about your future.
What Exactly Is the Student Aid Index (SAI)?
The Student Aid Index (SAI) is a number generated after completing the FAFSA, serving as the primary metric colleges use to assess your financial assistance needs. Unlike its predecessor, the EFC, the SAI can be negative (as low as -1500). This change more accurately reflects significant financial need and can potentially make more students eligible for federal Pell Grants and other aid.
Think of the SAI not as a dollar amount you pay, but as a standardized index that helps financial aid administrators understand your family’s financial strength relative to college costs. A lower SAI generally indicates higher financial need, opening the door to more grants, scholarships, and subsidized loans. Conversely, a higher SAI suggests less financial need, typically leading to aid packages with more unsubsidized loans.
How Is the SAI Calculated? The FAFSA's Central Role
Your Student Aid Index calculation is founded on information provided in your FAFSA. This application gathers details about your family’s financial situation, including income, assets, and household demographics. The Department of Education then applies a standardized formula to this data to arrive at your unique SAI, creating a holistic picture of your ability to contribute to college costs.
- Your (and your parents', if dependent) Adjusted Gross Income (AGI)
- Taxable and untaxed income sources
- Certain assets (e.g., savings, investments, excluding primary home equity and retirement accounts)
- Family size and the number of family members attending college
- Marital status of parents (for dependent students) or student (for independent students)
The SAI calculation uses specific rules and weights for financial components; income generally carries more weight than assets. Accurately completing your FAFSA is paramount, as errors directly impact your SAI and aid eligibility. The FAFSA Simplification Act aimed to streamline this process, making it less burdensome for families to provide necessary information.
Decoding Your SAI Number: What It Means for Your Aid Package
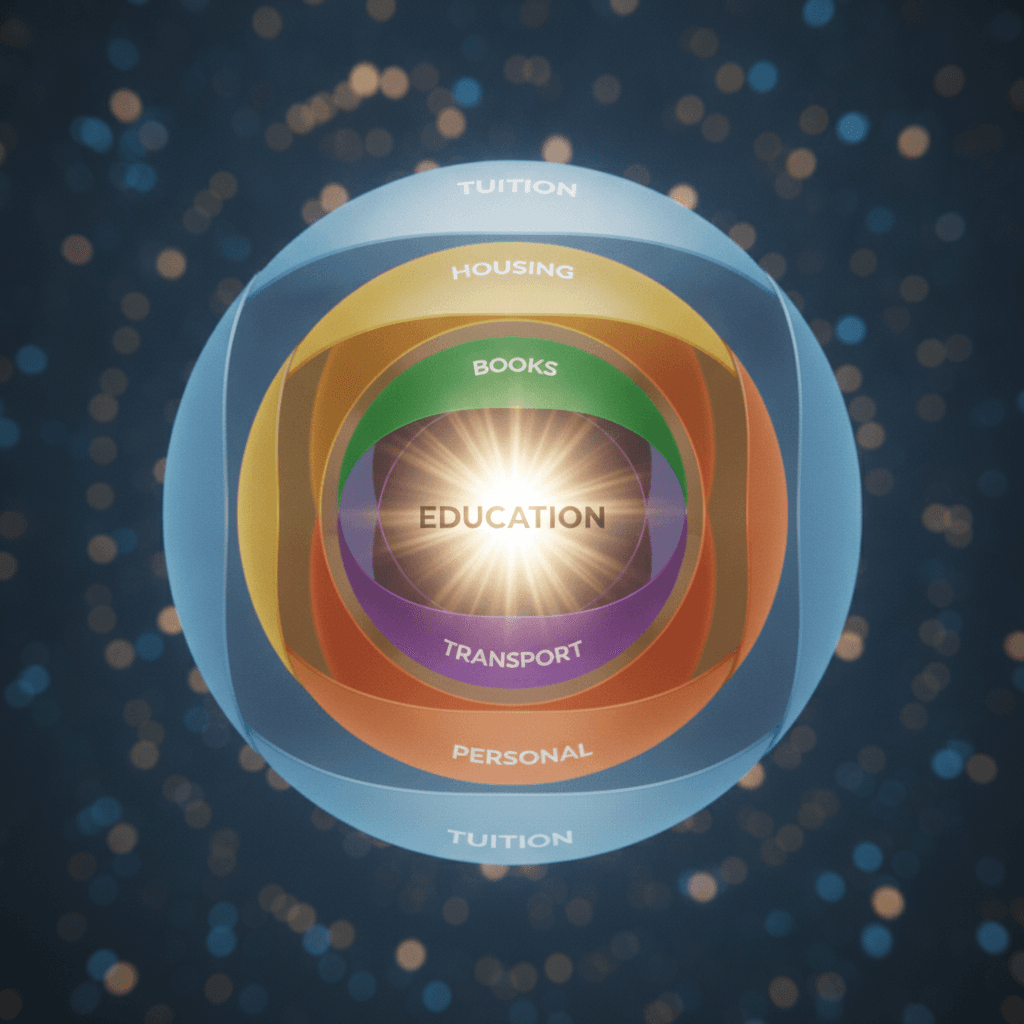
Once you receive your SAI, understanding its significance for college funding is key. Colleges use your SAI with their Cost of Attendance (COA) to determine your financial need. The formula is: Cost of Attendance (COA) - Student Aid Index (SAI) = Demonstrated Financial Need. The COA estimates all expenses for a year of college, including tuition, fees, room, board, books, supplies, transportation, and personal costs.
A lower SAI means higher demonstrated need, making you eligible for more need-based aid. Aid typically comes as grants, scholarships, federal work-study, and loans. A negative SAI indicates very high financial need, potentially qualifying you for maximum federal Pell Grant aid; it signifies substantial need, not that the school owes you money.
Conversely, a higher SAI means lower demonstrated need. Colleges might then offer aid primarily in unsubsidized loans, as grants are typically reserved for those with greater need. Remember, different schools have varying COAs and abilities to meet need, so aid packages can differ significantly.
The Shift from EFC to SAI: A New Era for Financial Aid
The Student Aid Index is a direct result of the FAFSA Simplification Act, a legislative effort to overhaul federal student aid. This change aimed to make the financial aid process less confusing, more equitable, and more accessible. The term "Expected Family Contribution" often caused confusion, leading many to believe it was the exact amount they would have to pay out of pocket.
By renaming it the Student Aid Index and allowing for negative values, the Department of Education clarified that this number is an index, not a direct billing amount. The new methodology also revised how certain assets and income sources are treated, potentially increasing the number of students eligible for need-based aid. Expanded eligibility for Pell Grants is a major benefit for many low-income students.
Maximizing Your Aid: What to Do with Your SAI
Knowing your SAI is a powerful tool in college planning. It helps you anticipate financial assistance and compare aid offers from different institutions effectively. Use your SAI and the college's COA to understand how much of your demonstrated need they are meeting, and with what types of aid (grants, scholarships, loans, work-study). This comparison is vital for informed decisions.
If your financial circumstances change after submitting your FAFSA – due to job loss, medical expenses, or other significant events – you can appeal your financial aid offer. Contact the financial aid office at prospective colleges to explain your situation; they may reassess your need and adjust your aid package. Remember the FAFSA is an annual application; completing it accurately and on time each year is critical to continuing federal student aid, as your SAI reflects your financial situation at the time of application.
Sources & Further Reading
- What is the Student Aid Index (SAI)? — Federal Student Aid
- Apply for Aid: FAFSA — Federal Student Aid
- U.S. Code: Title 20. Education, Chapter 28. Higher Education Resources and Student Assistance — GovInfo
- 20 U.S. Code § 1087kk - Expected family contribution — GovInfo
- Federal Student Aid — Wikipedia